
Online money lending tricks leave citizens restless
“I asked for sh100,000, got sh75,000, but was asked to pay back sh120,000. This is daylight robbery targeting desperate people,” he said. Although sh25,000 was deducted from the requested amount, he was required to repay sh120,000 within eight days — effectively paying a sh45,000 financing cost on the sh75,000 received, or 60%. He cites Quick Sente, Mangu Cash, Zenka and Mara Loan, which he said offer similar services.
The mobile app loans are easily accessible, but with astronomical interest rates.
SPECIAL REPORT
KAMPALA - Once a payment is delayed, the pressure becomes worse. The collection agents have since adopted debt-shaming antics through rogue WhatsApp groups. From borrowing just sh50,000, you later bear the ignominy of assuring family members and phonebook acquaintances that you have never engaged in bestiality. Simon Masaba writes
It starts with a pop-up on your cellular phone screen. Not the champagne kind, but the familiar pop-up of a loan notification — the digital equivalent of someone whispering: “Take this little money; you will sort us out later.”
The amount looks harmless, almost laughable. And with just a few taps, your quick cash problem gets solved. However, what begins as a minor debt soon grows teeth.
One loan rolls into another, fees pile up, repayment dates arrive with the enthusiasm of an unpaid landlord, and, before long, that innocent sh50,000 morphs into an obligation that makes the borrower wonder whether the phone should be switched off or thrown into Lake Victoria.
Once a payment is delayed, the pressure becomes worse. The collection agents have since adopted debt-shaming antics through rogue WhatsApp groups.
From borrowing just sh50,000, you later bear the ignominy of assuring family members and phonebook acquaintances that you have never engaged in bestiality, as claimed by the collection agents in viral messages.
Oundo’s case
That story mirrors Anthony Oundo’s. A resident of Kigowa, Nakawa Division, he faced a medical emergency. He needed sh50,000. Immediate friends provided excuses. The thoughtful ones suggested he download a digital lending application and borrow the money.
The sh50,000 was quickly deposited into his mobile wallet. The relief was palpable. It, however, did not last.
The loan came with a 15% interest charge and was expected to be repaid within three days (72 hours). By the fourth day, Oundo says, the pressure had begun. His phone rang off the hook.
The calls were interspersed with threatening messages. For weeks, he never had a decent wink of sleep, and bore the brunt of a litany of expletives from the moneylenders. He finally paid, but made one vow.
Never to borrow from phone apps. Oundo’s experience captures the contradiction at the heart of Uganda’s rapidly evolving digital credit economy; technology has made it easier to obtain emergency money, but for some borrowers, the same technology has put them off borrowing for sanity’s sake.
For a growing majority, it is not just about the sums due. It is about what happens to the information they surrender in exchange for measly sums.
Digital shylocks
Oundo is not alone. A prominent political and historical analyst, whose identity is withheld, recently described his experience with digital lenders on a talk show. He said he had used more than 20 lending applications because of the ease of accessing quick cash.
After borrowing from one app, he sometimes switched to another mobile line to escape persistent repayment calls, leaving him trapped in a revolving door of short-term credit.
For people with irregular incomes, he said, the attraction is obvious. Food, transport, rent, medical bills and other expenses do not wait for payday, while the smartphone is always within reach.
A media personality, also speaking anonymously, described another experience that made him question the true cost of instant credit. He called digital lenders “modern-day Shylocks.”
“I asked for sh100,000, got sh75,000, but was asked to pay back sh120,000. This is daylight robbery targeting desperate people,” he said.
Although sh25,000 was deducted from the requested amount, he was required to repay sh120,000 within eight days — effectively paying a sh45,000 financing cost on the sh75,000 received, or 60%.
“The lender initially asked for guarantors before advancing the money. The pressure did not wait for the deadline. I received notifications to clear the debt five days before the eight-day repayment period expired,” he said.
After the deadline, he said, reminders turned into a barrage of calls, some abusive. He summed up the experience colourfully: Lenders “offer a rabbit and demand a cow.”
His experience highlights why borrowers must distinguish between the amount requested, the amount actually disbursed and the total repayment demanded.
He acknowledges, however, that borrowing limits can rise for regular customers who repay on time, creating another incentive to keep using the apps. For university students, the financial emergency rarely waits for the next allowance
One minute it is transport money. The next, it is a tuition balance, hostel rent, food or an examination-related bill. And when friends and family have no cash to spare, the bright promise of “instant money” on a smartphone can be difficult to resist.
A university student interviewed for this story, whose identity has been withheld, found themselves in that exact situation after running short of money before the next allowance. A digital lending app appeared to offer an easy escape. A few taps later, the money was in the account.
The problem came later. The loan was small, but so was the repayment window. Before the student had figured out where the next batch of cash would come from, the deadline was already knocking.
With no regular income, a student who cannot meet the first repayment may turn to another source of money, sometimes another digital loan or simply to clear the first one.
One emergency can therefore become two loans, then three, with each fresh borrowing buying a little more time while adding another repayment date to the calendar.
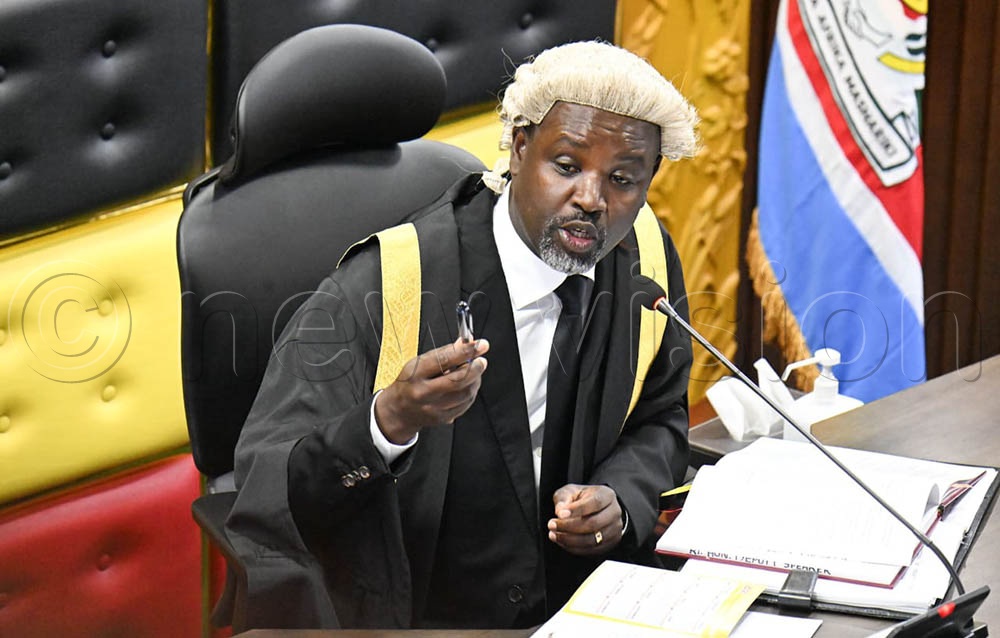
Deputy Speaker Thomas Tayebwa
For students whose finances depend largely on allowances from parents, relatives or other irregular sources of income, the squeeze is particularly intense. The vulnerability is not limited to students or people without professional qualifications.
Rogers Makuma, a lawyer operating in Mbale town, says people working a stable stream of clients find themselves in that borrowing web. For a lawyer keen to make impressions, cash has to come in handy all the time. Cue the digital loans.
“Borrowing is not necessarily confined to people without professional qualifications,” Makuma says.
His experience adds another dimension to the digital-credit debate: access to a professional occupation does not necessarily translate into a predictable monthly income.
In Kamwokya’s Elisa Zone, Akram Mbabazi, a butcher, represents another category of borrower drawn to quick digital credit: the informal-sector trader.
Running a small meat business means dealing with daily expenses, suppliers and customers whose payments may not always arrive when expected.
For such a trader, access to money through a mobile phone can provide an immediate bridge when cash runs short. But the same unpredictability that makes the loan attractive can make repayment difficult.
Unlike a salaried worker with a known payday, a small trader may not know exactly how much money the next day will bring.
Digital credit has, therefore, moved beyond the traditional image of a bank customer with a salary account. This cobweb also reached the doorsteps of Deputy Speaker Thomas Tayebwa.
He recently said that in 2024, he had personally experienced harassment linked to online lending. He said a lender had threatened him over a debt allegedly taken by someone who listed his name and contacts as a next of kin.
Tayebwa said his wife had also received similar threats. He called for stronger regulation of digital lenders, arguing that the sector needed monitoring to curb harassment and abuse.
Regulators’ take
UMRA directed digital credit providers to stop harmful lending practices and comply with the Digital Lending Guidelines, 2024, alongside other applicable laws and regulations
The authority also warned that administrative measures could be taken against licensed institutions that fail to comply with the regulatory framework. The regulator’s intervention places consumer protection at the centre of the digital-lending debate.
Digital credit can widen access to finance, particularly for people who may struggle to meet the requirements of conventional financial institutions. But easier access also creates a responsibility to ensure that borrowers understand the cost of the money they are receiving and that their personal information is handled lawfully.
Citizen complaints have also reached Parliament, with MPs saying that some digital money lenders have now pitched camp in remote rural areas across the country, targeting vulnerable citizens.
Lawmakers on Parliament’s Committee on Commissions, Statutory Authorities and State Enterprises (COSASE) say that the cost of digital credit is predatory. MPs said the cost of short-term digital loans and the methods used to recover them must be probed.
The legislators also questioned the practice of lenders accessing contacts stored on borrowers’ phones and the use of those contacts to exert pressure when repayments lag.
In his previous 2024/2025 report, the Auditor General (AG) also questioned the county’s credit regulatory framework, noting that it disproportionately favours leaders, leaving borrowers exposed to exploitation as the informal digital lending market expands.
Responding to the AG’s 2024/2025 queries during an interface with Parliament’s Public Accounts Committee (PAC), the secretary to the treasury, Ramathan Ggoobi, said: “We have a credit reference bureau that protects lenders, but there is a gap on the side of borrowers. We are now putting in place a mirror system where borrowers can also access information about lenders, especially to address bad practices, particularly in the informal tier four space.”
Uganda operates a Credit Reference Bureau system under the Financial Institutions Act, but lawmakers argue that the framework fails to protect consumers from predatory lending, especially by unregulated moneylenders operating under Tier four financial services under the Tier 4 Microfinance Institutions and Money Lenders Act, 2016.
What the law says
Uganda’s digital lending framework places limits on what lenders should be able to do with information on a borrower’s phone.
The Uganda Microfinance Regulatory Authority (UMRA) Digital Lending Guidelines, 2024, state under guideline 9 (3) that a digital credit provider shall not use digital means or applications that allow software to access a customer’s contact list, frequently dialled contacts and phone messages as a way of conducting electronic know-your-customer checks or managing delinquency.
The provision is significant because access to a borrower’s phone can expose information far beyond the financial details required to process a loan. A mobile phone can contain family contacts, business relationships, private conversations, photographs and communications from social-media platforms.
Once such information is accessible, the distinction between collecting a debt and intruding into a borrower’s private life can become blurred.
Experts speak out
Veronica Watsemba, a criminologist, says the phenomenon should also be examined from the perspective of vulnerability and behaviour. The attraction is straightforward.
The borrower does not have to travel to a bank, negotiate with a loan officer or provide conventional collateral. She says that for someone with a stable salary, a short repayment period may be manageable. But for students, casual workers and others, deadlines are often difficult to meet.
On the question of who the faces behind digital money lending platforms are, Conrad Johnson Wasike, an entrepreneur at Satolux Holdings Limited, says: “Uganda never ceases to amaze me. Courts can fault a lender for charging 12% interest per month, describing it as unconscionable, yet some telecom-based loan products charge as much as 0.95% per day. That translates to about 28.5% per month.”
On his part, Godfrey Ayuku, another concerned citizen, says: “Telecom companies often describe these loans as unsecured. Yet when you apply for a loan from a commercial bank, you may first have to clear outstanding telecom loans. This raises questions about how these digital loans are treated within the financial system.”
Experts say the issue of data protection also comes into play. Gilbert Ssettuuma, a legal officer handling compliance and investigations at Uganda’s Personal Data Protection Office, says the financial sector requires particular attention because personal data is central to lending operations.
Speaking during a data-protection training for staff of Mogo Loans Uganda, Ssettuuma argues that the regulator’s role includes ensuring that institutions entrusted with personal information understand their obligations under Uganda’s data protection framework.
On digital money lending, Hannington Kaleba, the head of the legal team at Mogo Loans, used the data protection training to amplify the need to build a culture of privacy, accountability and lawful data processing.